Bank Statement Programs
Some programs may review business or personal deposits and cash flow as an alternative way to document income, subject to program guidelines and underwriting.
For self-employed borrowers
Bank statement and other alternative-documentation programs may let a lender review deposits or business cash flow alongside the rest of your file, instead of relying on tax returns alone. Availability is subject to program guidelines, underwriting, and eligibility.
Ted Canto, Senior Loan Officer / Branch Manager · NMLS #228393 · Licensed in AZ, CA, FL, TX, VA
A more complete question
How does your business actually make money?
That answer can be more useful than a single line on a tax return. Ted will help you understand which documents may tell the story clearly.
Sounds like you?
Your income is real, but your tax return may also show deductions that change the picture a lender sees.
The money moves through the business, the truck, and the season. You want someone to look at the whole pattern.
Strong deposits can sit beside legitimate costs for people, tools, materials, and vehicles.
Revenue can be uneven even when the business is healthy. The timing and source of deposits may matter.
How qualifying can work
Some programs may consider 12 or 24 months of business or personal bank statements, or a profit-and-loss approach, instead of relying only on a tax return. That does not remove underwriting. It changes which parts of the story may be reviewed.
Deposits and expenses
A lender may review where deposits come from, business expenses, transfers, and the consistency of the overall cash flow.
Ownership and business
The business type, ownership interest, time in business, and how the income is documented can affect which programs are available.
The rest of the file
Credit, reserves, debts, the property, and the purpose of the loan typically remain part of the conversation.
Program and lender fit
The right documentation path can depend on the lender, property, transaction, applicable guidelines, and eligibility.
Who this may fit
Who it may not fit
If you are salaried and your documentation fits a conventional or government loan, that may be the cleaner answer. Ted will tell you if a standard loan is the better answer—even when it is not the path you expected to hear about.
Loan options at a glance
These are conversation starters, not promises or a complete list of available programs. Availability can depend on the lender, transaction, property, documentation, and eligibility.
Some programs may review business or personal deposits and cash flow as an alternative way to document income, subject to program guidelines and underwriting.
A lender may consider a borrower-prepared or accountant-prepared profit-and-loss statement alongside other documentation, depending on the program.
Certain programs may consider eligible assets as part of the income picture. The assets, documentation, and calculation can depend on the lender.
For an investment property, some programs may focus more on the property’s projected cash flow than on personal income. This is for investor scenarios, not every purchase.
If your income and documentation fit standard underwriting, a conventional loan may be the cleaner answer. Ted will tell you when it is.
FHA financing may be an option for eligible owner-occupied buyers, with documentation and property requirements set by the program.
Eligible veterans and service members may have VA options. Qualification, entitlement, property, and underwriting requirements apply.
Eligible buyers in qualifying areas may have USDA options. Availability and eligibility depend on the program, property, and borrower.
Higher-balance financing may be available for some properties and borrowers, with documentation and underwriting that can vary by lender.
Some programs may combine a purchase or refinance with renovation or construction financing when the property and project fit the lender’s requirements.
The MOVE Method™
Four practical steps keep the conversation grounded in your goal and the details that can affect the financing path.
Start with the complete picture: the business, the deposits, the goal, and the property.
Look for a structure that respects how your income actually arrives and what you are trying to do.
Pressure-test the documents, assumptions, cash needs, and program fit before a major decision.
Move forward when the scenario, documentation, and path are aligned.
Evidence / experience
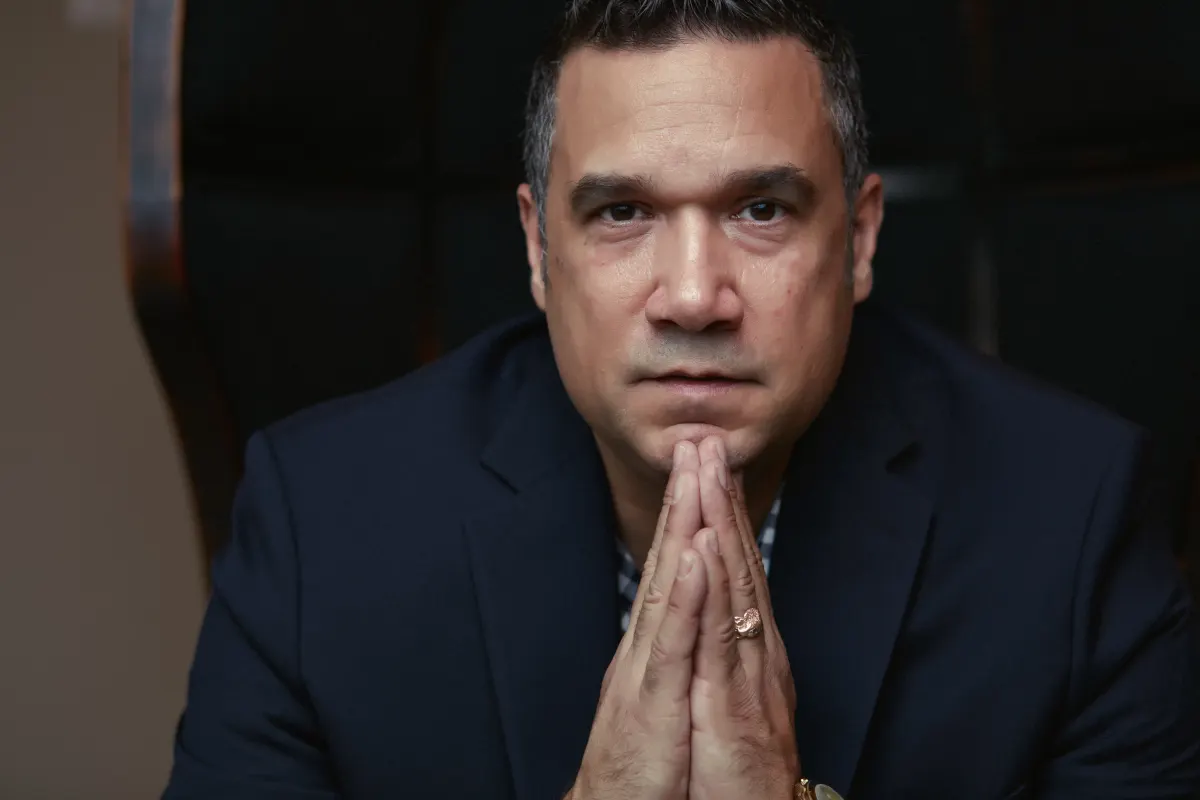
Ted Canto is a Senior Loan Officer and Branch Manager with approximately 28 years in mortgage and lending. His role is to make the details useful: what may matter, what may be missing, and when a standard loan could be the better path.
NMLS
Ted Canto #228393
Licensed in
Arizona, California, Florida, Texas, Virginia
Start with a question
Keep it simple. No sensitive financial information is needed here. A short note gives Ted a place to start the conversation.
A clearer next move
Start with a plan if you are still exploring. Apply when you are ready to share a full application.
Questions self-employed borrowers ask
Not always. Some alternative-documentation programs may consider business or personal bank statements, a profit-and-loss approach, or eligible assets instead of relying only on tax returns. Tax returns may still be requested, and the answer can depend on the program, lender, property, and the rest of your file.
It can. A lender may look at the pattern of deposits, the reason for the change, the business, and the most recent information available. A lower tax-return income does not automatically answer the question, but no program can ignore the full financial picture.
Not necessarily. The available path may depend on your business history, current records, statements, ownership, and the program’s documentation rules. Ted can help you understand what would need to be reviewed before you decide how to proceed.
Expect the conversation to cover deposits, business expenses, ownership, credit, reserves, debts, the property, and the purpose of the loan. The exact documentation and underwriting review can depend on the lender and program.
Possibly. Some investor programs, including DSCR-style approaches, may evaluate the property’s cash flow differently from an owner-occupied loan. The property, lease or market-rent information, reserves, and other eligibility factors can matter.
No. If a conventional, FHA, VA, USDA, or another standard option fits your documentation and goal, it may be the better answer. Ted will tell you when the straightforward path makes more sense.
Compliance & corporate information
Ted Canto — Senior Loan Officer / Branch Manager — NMLS #228393
Canopy Mortgage, LLC — NMLS #1359687
Information provided on this website is for general informational and educational purposes only and does not constitute an offer, commitment to lend, loan approval, qualification, prequalification, or guarantee of financing. All loan programs, financing options, terms, rates, conditions, and availability are subject to change without notice and are subject to applicable lender and investor guidelines. Loan approval and program eligibility are subject to, but not limited to, verification of credit, income, employment, assets, debts, property eligibility, appraisal, acceptable collateral, underwriting requirements, and all applicable loan program guidelines. Not all applicants will qualify.
Equal Housing Opportunity